Repair or Replace? How to Decide on an Aging Florida Roof
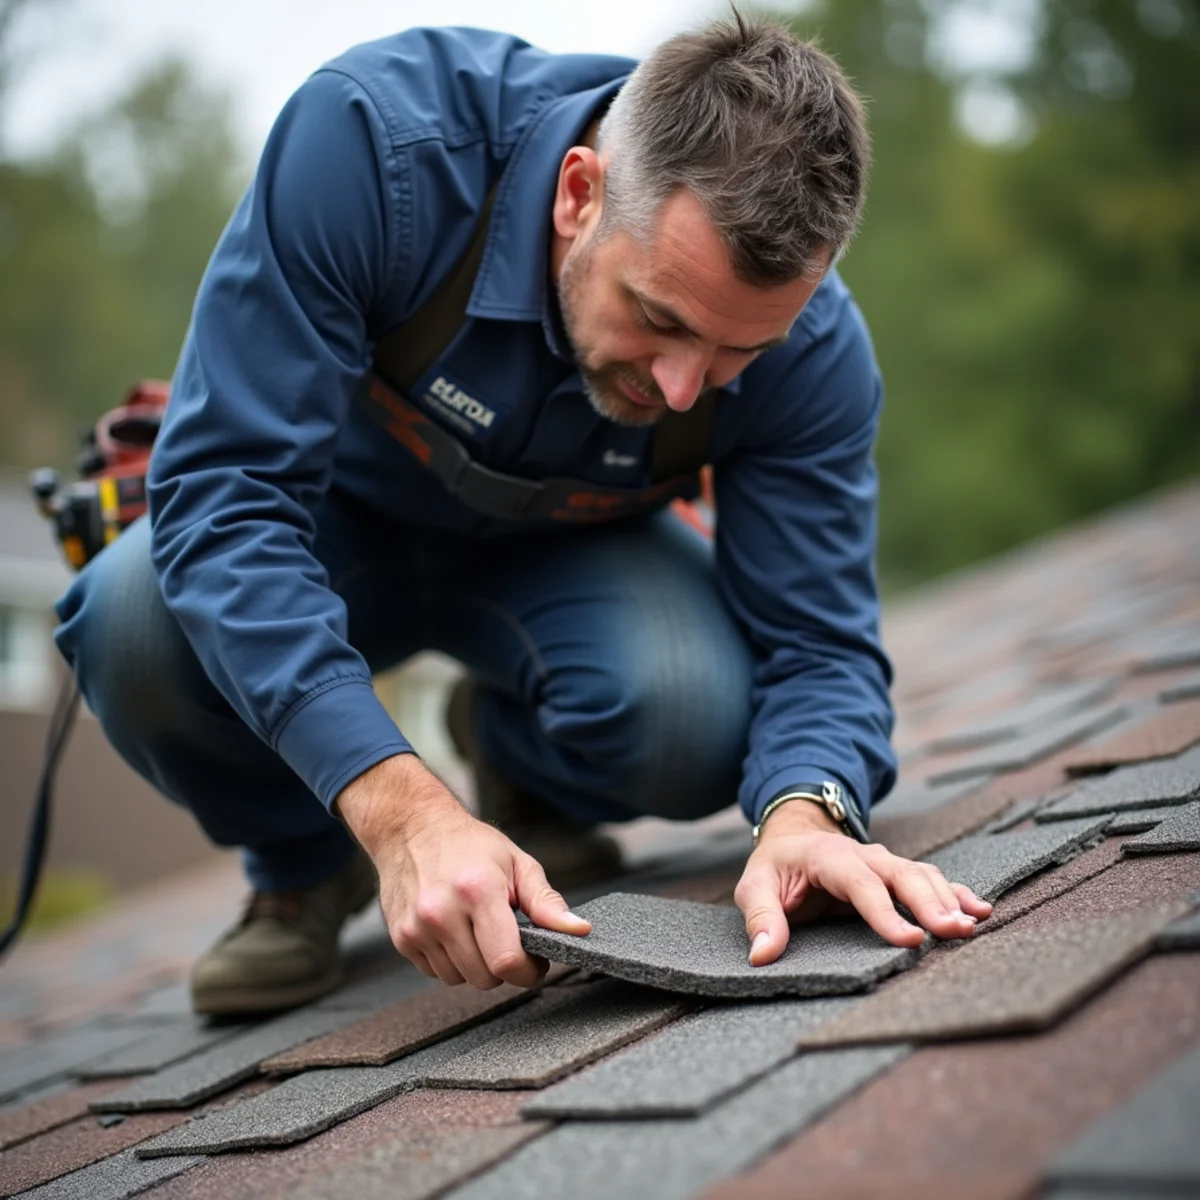
To decide whether to repair or replace an aging Florida roof, evaluate the 25% rule, remaining lifespan, storm damage extent, and insurer requirements. If a shingle roof is over 15 years old, leaks in multiple spots, or has widespread granule loss and brittle tabs, full replacement is more cost-effective than repetitive repairs.
Key Takeaways for Florida Property Owners
- 1The 'Rule of 15': Shingle roofs over 15 years old in Florida usually warrant replacement over major repair.
- 2The Florida 25% Rule mandates full re-roofing if more than 25% of a pre-2007 roof is damaged within a 12-month period.
- 3Isolated leaks around pipe boots or chimney flashings on roofs under 10 years old are ideal repair candidates.
- 4Repairing brittle, non-flexible shingles often causes collateral damage to adjacent tabs.
- 5A new roof qualifies you for major wind mitigation insurance discounts that offset installation costs.
When a Localized Repair Makes Total Sense
If your roof is under 10-12 years old, the shingles remain pliable, and the problem is isolated (such as a cracked plumbing boot collar or a tree branch scratch), a targeted repair is fast, economical, and sensible.
When Replacement is the Smarter Financial Choice
If your roof is over 15 years old, has widespread granule depletion, exhibits multiple leaks, or has failing organic felt underlayment, pouring thousands into repeated repairs is a financial trap. A full replacement resets your insurance clock, earns wind mitigation discounts, and restores total home security.
Financial Analysis: Why Repeated Repairs Drain Homeowner Budgets
Spending $700 to $1,200 every six months chasing leaks on an 18-year-old roof is financially counterproductive. Those repair expenses produce zero return on equity and zero insurance premium discounts, whereas a planned re-roofing immediately raises appraisal value and cuts annual insurance costs.
Common Mistakes Florida Property Owners Make & Professional Guidance
In our 25+ years inspecting and installing roofs across Flagler, Volusia, and St. Johns counties, we regularly witness costly errors that void warranties or lead to denied insurance claims. First, homeowners often rely on unlicensed handymen or out-of-state storm chasers who fail to pull mandatory municipal building permits or neglect Notice of Commencement (NOC) filings. Second, many attempt DIY repairs using silicone caulking or black roof tar, which traps moisture beneath shingles and accelerates decking rot. Third, property owners frequently delay filing storm claims past Florida statutory deadlines or accept lowball initial adjuster estimates without obtaining an itemized contractor quote. Always partner with a verified, Florida state-certified roofing contractor (CCC) who provides written warranties, pulls local permits, and verifies Florida Product Approval compliance on every material.
| Condition Indicator | Recommended Action | Primary Reason | Cost Comparison |
|---|---|---|---|
| Single pipe boot leak on 7-year roof | Repair ($350 – $650) | Roof field is sound; isolated component failure | Saves $10,000+ vs replacement |
| Multiple leaks across 16-year roof | Replace ($9,000 – $15,000) | Underlayment dried out; ongoing leak risk | Repairs cost more over 24 months |
| Storm damage to 30% of roof slopes | Replace (often Insurance Claim) | Florida code threshold & structural wind load | Covered under windstorm policy |
| Discontinued shingle color mismatch | Replace (Matching Statute) | Preserves aesthetic uniformity and home value | F.S. 626.9744 compliance |
“We never push homeowners into an unnecessary roof replacement if a repair will genuinely give them 3 to 5 more reliable years. But if we climb on your roof and the shingles are as brittle as potato chips, trying to slide new shingles underneath will crack every surrounding tab. We give you honest, unbiased diagnostics so you make the right call.”
— Tim Farrell, Co-Owner — Repel Dry LLC
5 Immediate Steps for Florida Property Owners
Whether you are preparing for hurricane season or responding to suspected storm or wind damage, follow this contractor-verified checklist to protect your home and legal rights:
Photograph all four exterior elevations, gutters, fallen tree branches, displaced shingles, and interior ceiling water spots before any cleanup or emergency tarping begins.
Florida insurance policies require homeowners to take reasonable steps to prevent further damage. Install secured tarps over penetrations without nailing directly through good shingles.
Review your insurance declarations page. Hurricane deductibles are typically 2% to 5% of your home's insured dwelling limit (Coverage A), whereas regular wind/water deductibles are often lower fixed amounts.
Never sign an Assignment of Benefits (prohibited under Senate Bill 2A) or work with canvassers who lack an active Florida Certified Roofing Contractor license (verify on MyFloridaLicense.com).
Schedule an on-site physical walk with a local state-certified builder who can inspect roof decking, underlayment adhesion, valley flashings, and attic moisture patterns.
Key Florida Roofing & Insurance Statutes Every Property Owner Must Know
Florida construction and insurance regulations underwent major reforms in 2022 and 2023. Here are the core statutory requirements that govern residential and commercial roof repairs in our state:
Establishes a strict 1-year deadline from the date of a windstorm or hurricane event to give initial written notice of a property damage claim to your insurance carrier. Supplemental claims must be filed within 18 months.
If more than 25% of a roof section is damaged within a 12-month period, the entire roof section must be upgraded to comply with the current Florida Building Code, unless the existing roof was installed under the 2007 FBC or later.
Eliminated post-loss Assignment of Benefits (AOB) for residential property insurance. Homeowners remain the direct policyholders and must be issued insurance claim payments directly by their insurer.
Unlicensed contracting during a declared state of emergency is a third-degree felony in Florida. Always insist on seeing an active DBPR Certified Roofing Contractor license (CCC license) before any roof work begins.
Verified Under Florida Building Code 8th Edition (2023)
This technical guide is authored and reviewed by licensed Florida roofing and building contractors Tim Farrell and Chris Howard of Repel Dry LLC (FL Lic # CCC1332106, CBC1264358, CRC1332435). All structural recommendations comply with the Florida Building Code 8th Edition (2023), ASTM D1970 secondary water barrier requirements, and Florida Statutes governing property insurance disclosures (F.S. § 627.70132 and F.S. § 626.9744).
Summary & Next Steps for Your Roof
Navigating Florida roofing decisions requires factual guidance, strict adherence to Florida Building Code 8th Edition (2023), and an experienced local team you can hold accountable. Repel Dry LLC is headquartered at 2323 N State St in Bunnell and provides free on-site inspections throughout Flagler, Volusia, and St. Johns counties.
Related Professional Services & Areas
Need assistance with issues discussed in this guide? Explore our specialized solutions:
Related Services:
Related Local Areas: